TL;DR – Quick Insights on Where to Get a Fidelity Bond
Looking for the right place to secure a fidelity bond doesn’t have to be overwhelming. You can get bonded through surety bond specialists, insurance providers, or online platforms that simplify the process. Understanding the party to a surety or fidelity bond — principal, obligee, and surety — helps you make smarter decisions. Meeting requirements upfront speeds approval and ensures protection for your business and its assets.
Understanding Fidelity Bonds Before You Buy
Fidelity bonds protect businesses, HOAs, ERISA plan sponsors, and clients from financial losses caused by employee dishonesty, fraud, or theft. Unlike general insurance, they specifically cover dishonest acts like embezzlement, forgery, or theft of funds. Whether you are a small business owner or an HOA board, knowing where to get a fidelity bond is the first step toward compliance and peace of mind.
The Party to a Surety or Fidelity Bond: Principal, Obligee, and Surety Explained
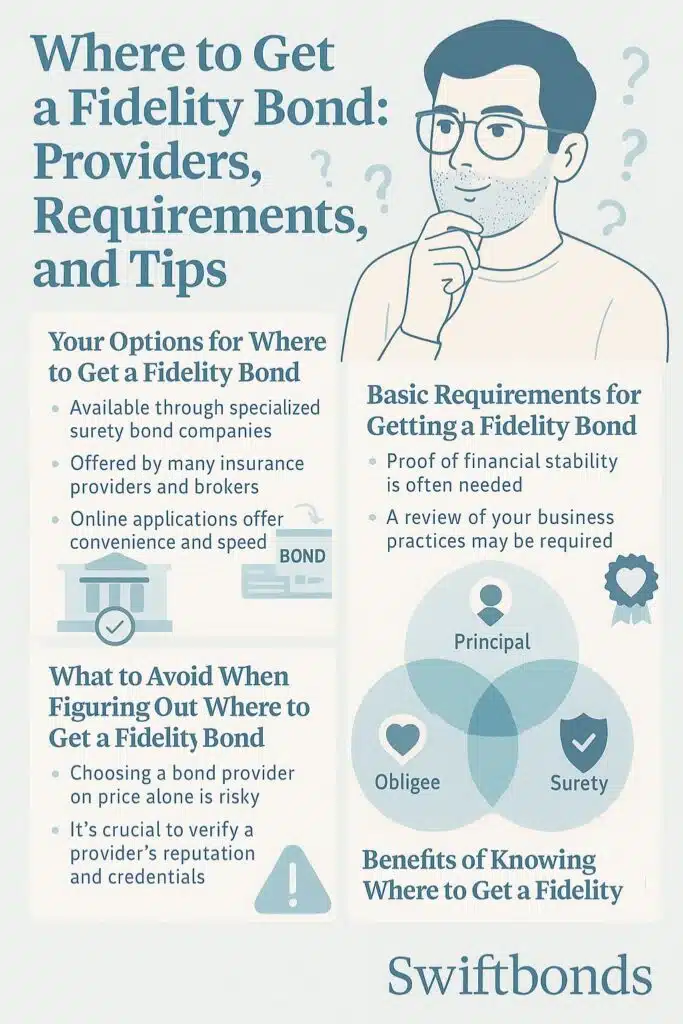
To make an informed choice, it’s important to understand the party to a surety or fidelity bond. The principal is the person or business purchasing the bond and promising honest conduct. The obligee is the entity requiring the bond, such as a state agency, HOA, or employer. The surety is the bonding company that guarantees payment if the principal fails to meet obligations. Knowing these roles clarifies why the bond exists — it builds trust between all parties and ensures restitution if wrongdoing occurs.
Every fidelity bond has three critical parties:
Principal (that’s you).
The principal is the entity applying for the bond — your business, HOA, or plan sponsor. By purchasing the bond, you agree to follow the rules set by the obligee. If a valid claim is paid, you must reimburse the surety under the indemnity agreement.
Obligee (the one requiring the bond).
The obligee is the party requiring and benefiting from the bond. This could be your ERISA plan, HOA, client, or a state agency. They set the bond amount, language, and compliance requirements.
Surety (the company backing the bond).
The surety is the licensed bond company that underwrites and issues the bond. Think of them as providing a financial guarantee rather than insurance — they pay claims to the obligee but expect reimbursement from the principal.
Example:
If an HOA treasurer misappropriates funds, the HOA (obligee) files a claim, the surety pays out up to the bond limit, and the HOA (principal) must reimburse the surety.
This section is key when selecting a provider — you must supply correct principal information, confirm the obligee’s bond form, and work with a surety that understands your industry’s risk.
Common Roadblocks in Getting a Fidelity Bond
Delays usually come from missing paperwork, applying for the wrong bond type, or not meeting the obligee’s form requirements. Many business owners mistakenly treat fidelity bonds like general insurance and fail to provide financial information or sign the indemnity agreement, slowing approval. Swiftbonds eliminates these bottlenecks by gathering all required information upfront.
Swiftbonds’ Role in Making the Process Easy
Swiftbonds acts as your expert guide, connecting you with A-rated surety providers that specialize in fidelity bonds. Our process is quick, transparent, and designed to help you avoid compliance mistakes. We clarify obligee requirements, secure competitive rates, and issue bonds fast — often within 24 hours.

Step-by-Step Guide to Getting Your Fidelity Bond
-
Identify the obligee requirements – confirm bond form and coverage amount.
-
Gather your documents – business license, financials, or HOA/plan details.
-
Apply with Swiftbonds – we match you with the right surety.
-
Sign indemnity agreement – required by all surety companies.
-
Receive your bond – delivered electronically or overnight.
-
Keep copies for compliance – and renew annually if required.
See our post about the Where to Get a Fidelity Bond: Providers, Requirements, and Tips
The Cost of Skipping a Fidelity Bond
Failing to obtain a fidelity bond when required can lead to legal penalties, loss of licensing, or even lawsuits from clients or members. For ERISA plans, not having a bond is a federal violation and could trigger DOL audits.
The Long-Term Benefits of a Fidelity Bond
A properly issued fidelity bond builds credibility with clients, plan participants, and HOA members. It shows you are financially responsible and compliant. It also gives peace of mind knowing you have protection if employee theft or fraud occurs.
Know the Law: Official Statutes Governing Fidelity Bonds
-
ERISA §412 (29 U.S.C. §1112) – Requires fiduciaries and anyone handling plan assets to be bonded for at least 10% of plan funds, up to $500,000 (or $1M for employer securities).
-
Virginia Code §13.1-852.1 – Requires nonprofit HOAs to carry fidelity bonds covering officers and directors handling funds, often equal to reserves plus three months’ assessments.
-
California Code of Regulations §260.237.1 – Requires certain financial professionals to maintain a fidelity bond as a condition of registration.

Always verify state and federal statutes to ensure compliance before purchasing.
Frequently Asked Questions
What is the purpose of a fidelity bond?
It protects your organization from employee theft, fraud, or dishonest acts involving money or property.
How much coverage do I need?
Coverage typically matches regulatory requirements — ERISA requires 10% of plan assets, while HOAs may need reserves plus operating funds.
Can a fidelity bond be customized?
Yes, bond language can be tailored to meet obligee requirements, but it must be approved by the surety and obligee.
What happens if a claim is filed?
The surety investigates, pays valid claims to the obligee, and then seeks reimbursement from the principal.
Conclusion: Get Your Fidelity Bond the Right Way

Knowing where to get a fidelity bond — and understanding the roles of principal, obligee, and surety — ensures you stay compliant and protected. Swiftbonds guides you through the process, secures top-tier sureties, and delivers your bond quickly so you can focus on running your business.
See our post about the Fidelity Bond Real Estate Agents May Need for Escrow and Trust Protection
What Real Clients Say About Swiftbonds
From a Florida HOA President: “Swiftbonds made sure our fidelity bond met all state requirements and got it to us within 24 hours. Highly recommend!”
From a Texas Plan Administrator: “They explained the ERISA requirements clearly and handled everything from start to finish — smoothest bonding experience I’ve had.”